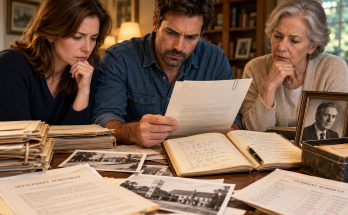
The morning after Helen Ward reviewed the recovered correspondence, Claire Bennett arrived at her solicitor’s office with a copy of her father’s green notebook tucked inside a plain brown folder. She had spent most of the previous evening comparing the dates in the notebook with the accounting summaries Northbridge Holdings had supplied. The figures did not yet establish where the disputed money had gone, but the gaps between the records were becoming harder to dismiss as ordinary mistakes.
Helen was already at her desk when Claire entered. Two thick files lay open before her, one containing Thomas Bennett’s correspondence and the other holding the documents produced by Northbridge. A third folder, marked with the name of Martin Shaw’s accounting firm, contained the latest transaction schedule.
“I want us to stop asking them for explanations in general terms,” Helen said. “We need the original records that support every important claim they have made. If they say the payment was legitimate, they must identify the obligation it satisfied. If they say the supplementary agreement gave them additional rights, they must produce the executed agreement and show how it was properly authorized.”
Claire set the notebook beside the files. “And if they cannot?”
“Then we document what is missing and consider the appropriate next step. We cannot automatically conclude that a missing record proves misconduct, but Northbridge cannot expect us to accept an accounting that relies on documents it cannot produce.”
Helen opened Martin’s revised schedule. The disputed payment had been made from the Mercer Street project account three days after Thomas’s death. The transaction was initially described in internal records as a closeout adjustment, while another record referred to supplementary security. The supporting schedule was incomplete when the payment was processed, and the later authorization appeared to have been entered after the transfer.
The money had first moved to Alder Consulting. From there, the trail continued through another intermediary, but the available records did not yet identify the ultimate beneficiary. Northbridge’s summary referred to project expenses without supplying the invoices, contractual terms, or detailed calculations that would allow Martin to verify the classification.
Helen drew a line beneath the entry. “This is the central financial question. We need the complete transaction ledger, the payment instruction, bank confirmation, recipient information, and the records supporting the stated purpose. We also need to know who requested the transfer and who approved it.”
Claire remembered her father’s handwriting beside the Westmere Advisory Services entry in the notebook: No schedule supplied. Ask for beneficial recipient.
“He was already asking the same question,” she said.
“Yes,” Helen replied. “That makes his concern relevant to the history of the project. It does not tell us what happened to the payment, but it shows that the missing information was not a concern invented by the estate after his death.”
Helen began drafting a formal disclosure request. She included every document category Martin had identified and asked Northbridge to explain the different descriptions attached to the transaction. She also requested all internal messages concerning the payment, including communications between Richard Cole, the finance department, the project administrators, and anyone responsible for reviewing the supplementary agreement.
The request specifically addressed the timing of the payment. Northbridge was asked to identify the person who decided that the transfer should proceed while the supporting schedule remained incomplete, the authority relied upon, and the date on which the final authorization was recorded. Helen also demanded any record showing that Thomas had approved additional security over Mercer Street.
Claire watched the letter take shape. It was precise and unemotional, which made it feel very different from the questions she had wanted to ask Richard directly. She wanted to know why he had kept the file, why he had asked Daniel for copies of her signatures, and why a payment had been made before the estate could inspect the accounts. Helen’s letter did not ask those questions in accusatory language. It required records that might answer them.
Once the letter was ready, Helen sent it through Northbridge’s solicitor. She also requested confirmation that the company had preserved the original paper files and electronic records. Given the missing folder, the incomplete scan, and the uncertain status of the supplementary agreement, she considered preservation essential.
Later that afternoon, Martin called with an update. He had compared the transaction schedule with the internal descriptions already available and found that the same payment appeared under different categories at different stages of the accounting process. One entry referred to closeout, another to supplementary security, and a later summary grouped the amount with general project expenses.
“Those labels are not necessarily incompatible,” Martin explained. “A payment might be associated with closeout and still relate to a security arrangement. But we need to know what obligation it actually satisfied. At present, the descriptions are doing more work than the supporting documents.”
Claire asked whether the money could have been paid for legitimate services that were simply poorly documented.
“It could have been,” Martin said. “That is one possibility. Another is that the payment was made before the relevant obligation was properly established. There are other possibilities too. I will not choose between them until we have the original entries and whatever supporting material exists.”
His caution frustrated Claire, but she knew it was necessary. A careless accusation could allow Northbridge to shift attention away from the missing records and toward her language. She agreed to wait for the financial evidence.
The next day, Northbridge’s solicitor acknowledged the disclosure request. The company said it was gathering information from several departments and former project personnel. It did not provide a timetable for the complete response, but it confirmed that the request had been referred to the finance and legal teams.
Helen considered the acknowledgment insufficient as an answer but useful as a record. She replied that the estate expected a substantive response and reiterated the preservation requirement. She also made clear that a general accounting summary would not satisfy the request for underlying documents.
Daniel contacted Claire that evening. He had learned that Northbridge was reviewing the project records and wanted to know whether the company had mentioned him. Claire told him that the request concerned the transaction and the documents, not an attempt to obtain a convenient confession from him.
“Richard told me this would all be settled by now,” Daniel said. “He said the estate would have no reason to question the project once the closeout was recorded.”
“Did he tell you that before or after the payment?”
“Before. He was talking about the project in general. I thought he meant the financial problems would finally be resolved.”
“Did he tell you what the payment was for?”
“He called it an adjustment. I never saw an invoice or schedule. I didn't ask for one.”
Claire paused before answering. “You were willing to let him use documents with my forged signature, but you never asked what he was doing with the money?”
Daniel did not defend himself. “I was trying to keep my own situation from collapsing. I convinced myself that if the project succeeded, everything else could be fixed. I know how that sounds.”
“It sounds like you decided my risk was acceptable because your own problems were urgent.”
“I know.”
Claire ended the call without another argument. His admissions were becoming more direct, but they did not make his earlier decisions less serious. Helen had told her that Daniel’s cooperation might help establish the sequence of events. It would not erase the need to determine what he had done or whether other people had used his actions to pursue their own objectives.
Two days later, Patricia Wells sent Helen an additional note. Patricia had reviewed the copies she preserved from her time as Richard’s administrative assistant and located an internal message concerning the project file. The message referred to the closeout payment and said that the file should remain together until the execution status of the supplementary agreement was clarified.
A separate note stated that the payment should be completed before the estate requested a full accounting. Patricia could not say who had written that note, but she remembered that it had circulated among people working on the closeout.
Helen forwarded both items to Martin. He added them to the timeline, carefully marking their sources and the limits of what they established. The records connected the timing of the payment with the unresolved agreement, but they did not identify the ultimate recipient or prove that the two issues had been deliberately linked.
Claire read the internal message several times. The words were administrative, almost dull. Yet the instruction to complete the payment before the estate requested an accounting gave her a reason to ask whether the urgency had been driven by a legitimate deadline or by the expectation that a new beneficiary would begin examining the records.
That evening, she returned to Thomas’s notebook. She found the entry about Westmere and placed it beside Patricia’s message. Her father had questioned the missing schedule before his death; someone later urged the payment to be completed before the estate requested an accounting. Between those two points lay the unanswered question of what the money had been intended to accomplish.
The following morning, Helen prepared a supplemental letter requesting the original project file, all versions of the supplementary agreement, and every record explaining why the payment was treated as ready for processing. She asked Northbridge to identify the person who wrote the note about the estate’s accounting request and explain whether the instruction had been approved by a finance officer.
“This is where we keep the investigation focused,” Helen told Claire. “We are not asking them to agree with our suspicions. We are asking them to produce the evidence that would either support or undermine those suspicions.”
Claire signed the instruction authorizing Helen to continue the inquiry. She knew it would take more time and might uncover facts that made the dispute more complicated. But Thomas had refused to grant additional security without a full accounting, and she had no intention of abandoning that condition merely because Northbridge preferred a quick settlement.
As Helen sealed the letter, Claire looked again at the empty space in the file where the complete transaction record should have been. The missing documents had become part of the story, but they were not the ending. Somewhere in the records of Northbridge, Alder Consulting, or the recipient beyond them, there should be evidence showing what had happened to the money.
She intended to find it.
Click here to continue reading: PART 26: The Money That Passed Through Two Doors
Three Days After the Funeral, My Husband Quit His Job and Made a Decision That Changed Everything
Part 25 of 35